



Practical guide
SFA/DMS and accounting: where the boundary sits
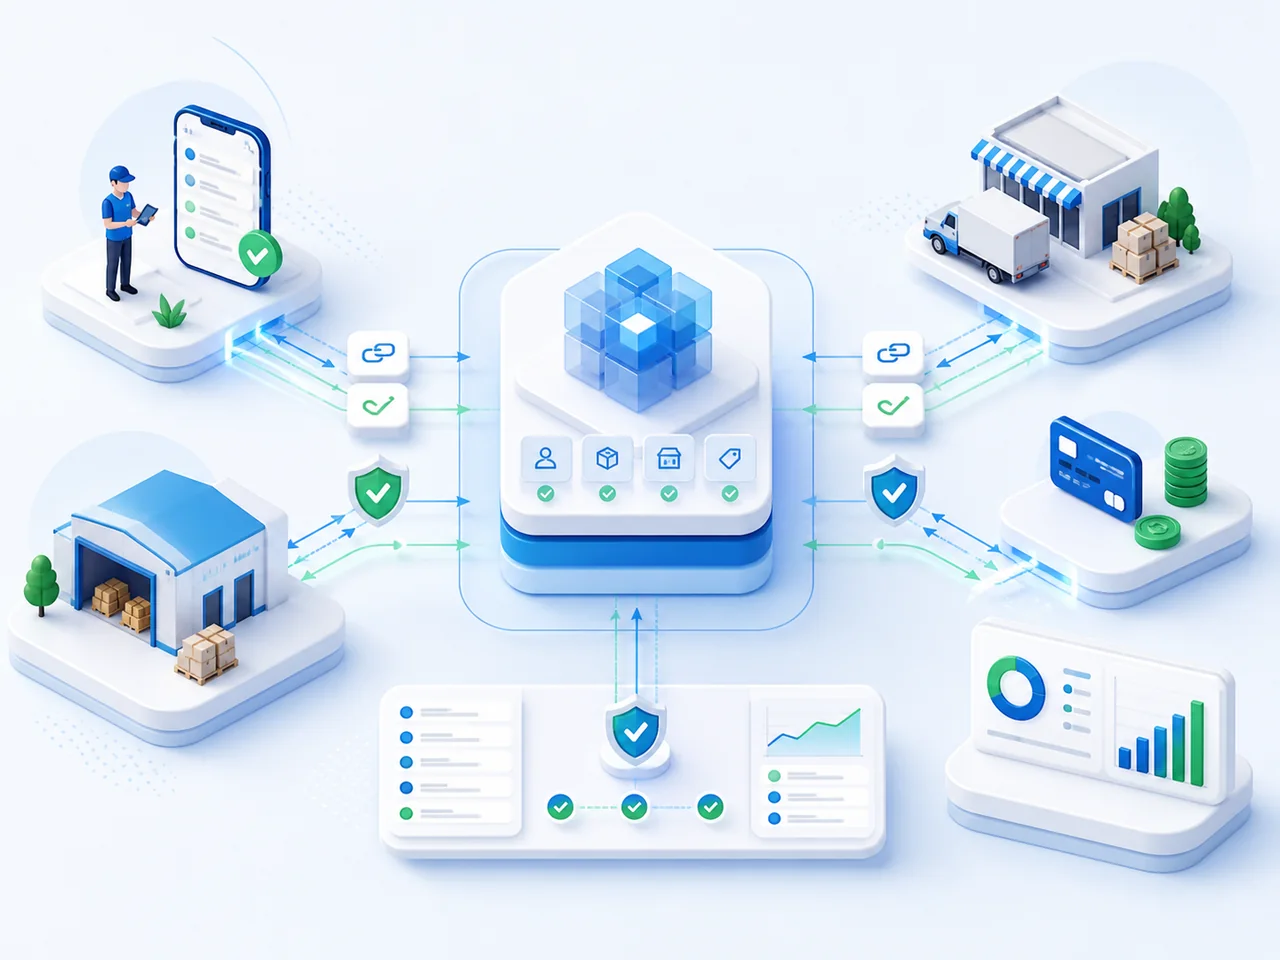
SFA and DMS manage distribution execution, while the accounting core owns accounting records, postings, inventory valuation and period close. Integration transfers agreed documents and statuses between these responsibilities.
- ERP and Accounting for Distribution
- Green Line Trading: product traceability, customer master data and delivery control
- For IT directors
In detail
This article is for sales, operations, finance and IT leaders connecting field activity with accounting. Assign ownership to a specific fact rather than an entire screen or order: who confirms demand, shipped quantity, receipt of money and the accounting entry? Each fact needs a source system, an accountable role and a correction rule.
Sent, received, document created and posted are different states. An integration response may acknowledge only receipt; neither an order nor delivery confirmation replaces accounting recognition. Agree which date each report uses: event date, document date or posting date. Keep the time of arrival in the other system separately. Comparison requires a common period, time zone and rule for late documents. Explain date differences before considering any authorised change to the accounting period.
One order may have several shipments, and documents may be consolidated under the agreed model. Preserve line links, quantities, units, versions and the remaining balance. Reconcile the same legal entity, agreed warehouses, currency and comparable statuses. Before comparing amounts, establish whether tax is included, where discounts are applied and how lines or documents are rounded. Matching totals do not prove matching lines: an omission and a duplicate can offset each other.
A promise to pay, an employee report of money received, a confirmed receipt and allocation of that payment to obligations are different facts. Do not equate a promise or screenshot with a settled debt. Reconciliation needs the payment reference, payer, currency, date and confirmed allocation; an advance does not necessarily settle a particular debt.
If a response is lost, the result is unknown: first look up processing by the original identifier, then follow the agreed retry rule. A corrected order needs an explicit version or change operation, not a blind replay of the old request. Physical return, permission to resell and accounting adjustment also require separate confirmation.
For the discussion, prepare an anonymised order with a partial shipment, payment and return, a system map and two extracts for the same agreed cut-off. Include report filters, date fields, an amount breakdown and a late-document example. In the pilot, distinguish an explained delay, a difference in calculation rules and a data error. Record the evidence, owner, action and recheck outcome for each discrepancy. The aim is a traceable result and an agreed correction process, rather than forcing two totals to match.
How it is applied
- Choose one process and collect linked anonymised documents, statuses and extracts from both systems for an agreed cut-off.
- Assign a source, accountable role, confirmation event and change rights to each fact or field.
- Record line links, versions, legal entity, warehouses, units, currency, date fields and time zone. Specify price components, discounts and rounding.
- Test partial fulfilment, unconfirmed payment, a return, a lost response and a retry. Include a late document at a period boundary.
- Reconcile lines and totals. Record each difference, its cause, owner, action and recheck result; then agree the launch conditions.
Practical checklist
- Each fact and field has a source, an accountable role and a change rule.
- Field users do not re-enter accounting facts.
- An exchange error is visible to the process owner and has a next action.
- The reconciliation rule is approved before production use.
Scope and limits
Responsibility depends on the selected architecture and accounting policy. This guide does not assume that SFA/DMS replaces accounting or that ERP should manage field execution.